
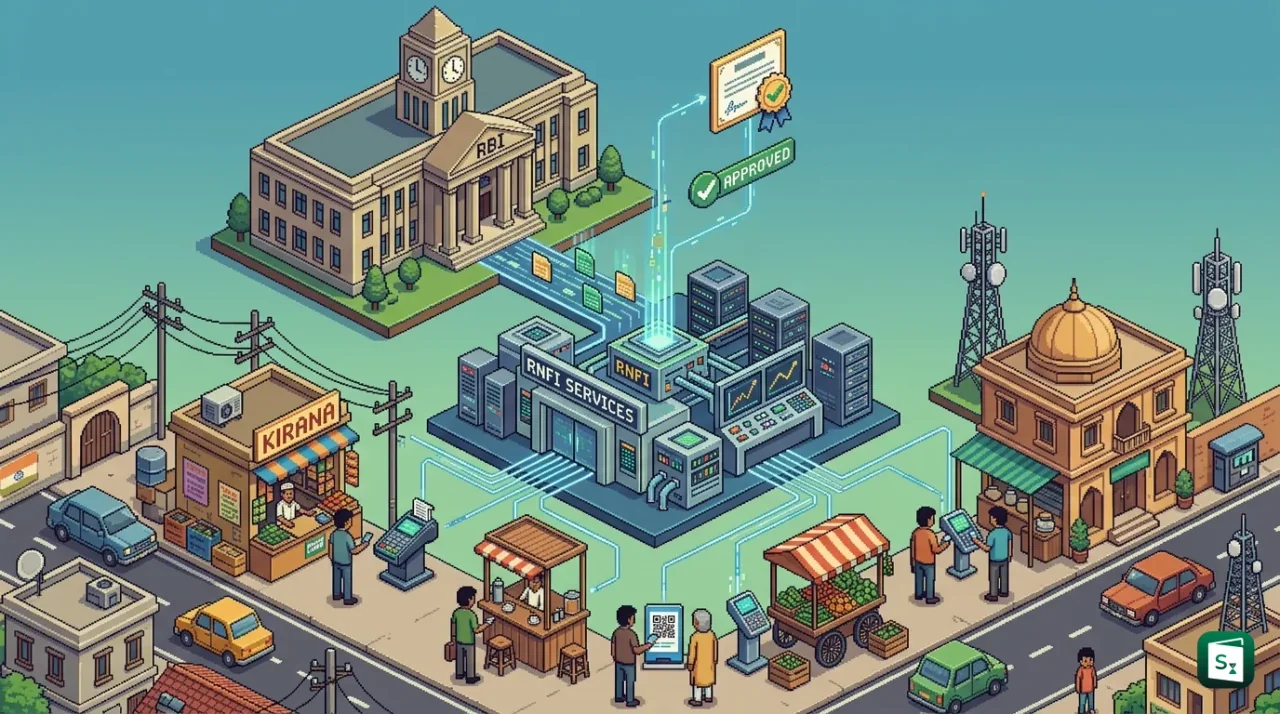
RNFI Services Ltd has received in-principle authorisation from the Reserve Bank of India (RBI) to operate as a Payment Aggregator-Physical (PA-P) under the Payment and Settlement Systems Act, 2007. The approval allows the listed fintech to aggregate payments for physical, offline and in-store transactions through its existing distribution network. With this, RNFI joins the growing list of non-bank entities entering a segment of digital payments that was unregulated until a 2025 RBI overhaul.
What Is a Payment Aggregator?
A payment aggregator is an entity that onboards merchants, collects payments from customers on their behalf, pools the funds, and then settles the money to the merchants. Because it temporarily holds other people’s money, a non-bank payment aggregator must obtain an authorisation from the RBI before it can legally operate.
The role is best understood through the funds flow. When a customer pays a merchant through an aggregator, the money does not go straight into the merchant’s bank account. It first lands in a dedicated escrow account that the aggregator maintains with a scheduled commercial bank. The aggregator reconciles these collections and then transfers the correct amount to each merchant as per an agreed settlement cycle.
This is what separates an aggregator from a pure technology provider. Because the aggregator touches and temporarily holds customer funds, it carries settlement, refund, and chargeback responsibility. That fund custody is precisely why the RBI subjects aggregators to licensing, minimum capital, escrow, and merchant due diligence rules. Well-known payment aggregators in India include Razorpay, Cashfree, BillDesk, PayU, and Amazon Pay.
What Is a Payment Aggregator-Physical (PA-P)?
A Payment Aggregator-Physical (PA-P) is a payment aggregator that handles transactions where both the payment instrument and the acceptance device are physically present at the same place at the time of payment. In simple terms, it covers face-to-face and in-store payments such as a customer tapping a card or scanning a QR code at a shop counter.
The RBI introduced this category through the Reserve Bank of India (Regulation of Payment Aggregators) Directions, 2025, issued on 15 September 2025. Before this, only online payment aggregators needed RBI authorisation. Offline or proximity payment aggregation, where the merchant and customer are physically face to face, sat outside the regulatory net.
The 2025 Directions created a single, unified framework and placed payment aggregators into three clear categories.
| Category | Full Form | What It Covers |
|---|---|---|
| PA-O | Payment Aggregator-Online | Transactions where the payment instrument and acceptance device are not in close proximity, such as e-commerce checkout |
| PA-P | Payment Aggregator-Physical | Transactions where the instrument and acceptance device are physically present close together, such as card taps or QR scans at a shop |
| PA-CB | Payment Aggregator-Cross Border | Aggregation of cross-border payments for permitted current account transactions |
The Directions also set out who must apply and by when. Entities already running a PA-P business with an existing Certificate of Authorisation had to inform the RBI to get a revised certificate. Entities running only a PA-P business had to apply for authorisation by 31 December 2025. Any entity that missed the deadline was required to wind up its business by 28 February 2026. Applications are made through the RBI’s PRAVAAH online portal.
Payment Aggregator vs Payment Gateway
The terms payment aggregator and payment gateway are often used interchangeably, but they are legally and functionally different. A payment gateway is only a technology layer that routes payment instructions. A payment aggregator actually handles the money.
This distinction decides who needs an RBI licence. A payment gateway never touches customer funds, so it does not need authorisation under the PSS Act. An aggregator holds and settles funds, so a non-bank aggregator must be authorised by the RBI.
| Feature | Payment Aggregator | Payment Gateway |
|---|---|---|
| Role | Onboards merchants, collects and settles funds | Routes and processes payment instructions |
| Fund handling | Holds funds in an escrow account | Never handles funds |
| RBI authorisation | Mandatory for non-bank entities | Not required |
| Merchant account | Shared infrastructure under one master account | Merchant needs its own account with a bank |
| Minimum net worth | ₹15 crore at application, ₹25 crore by year three | No such capital rule |
| Services | Onboarding, settlement, risk, refunds, compliance | Secure transaction routing and fraud checks |
The Legal Framework Under the PSS Act, 2007
The authorisation rests on the Payment and Settlement Systems Act, 2007 (PSS Act), a law that governs how payment systems operate in India. The Act came into force on 12 August 2008 and gives the RBI the legal power to regulate and supervise every payment system in the country.
The PSS Act declares the Reserve Bank of India as the designated authority for regulating and supervising payment systems. Under Section 4, no person other than the RBI may start or run a payment system without an authorisation from the RBI. Section 7 of the Act explains how the RBI issues or refuses that authorisation, and it lists the factors the central bank weighs before granting a licence.
These factors include the need for the proposed service, its technical standards and design, the security procedure, the manner in which funds will move, the financial status and management experience of the applicant, and the interests of consumers. The RBI also considers monetary and credit policy before deciding. The law directs the RBI to try to dispose of an application within six months of filing.
Critically, the PSS Act also states that any contravention of its provisions is punishable, including with imprisonment or fine under Section 26 of the Act. This makes RBI authorisation a legal requirement and not just a formality.
What Is RNFI Services and What Does It Do?
RNFI Services Ltd is a last-mile financial infrastructure company that operates under the Relipay brand. It was incorporated in 2015 and is headquartered at Kirti Nagar, New Delhi. The company runs a phygital network, meaning it combines physical shopfronts with digital technology, to deliver banking and financial services to rural and semi-urban customers.
Its business model is built on local shopkeepers who act as Sahayaks (assistants or agents). A Sahayak uses the Relipay platform to offer services such as domestic money transfer, Aadhaar Enabled Payment System (AEPS) cash withdrawals, mini statements, mobile recharges, utility bill payments, and railway and air ticket bookings. In return, the Sahayak earns a commission, and RNFI earns a share of the transaction value.
By the end of FY 2024-25, RNFI had grown its active Sahayak base by about 52%, from 1.4 lakh to 2.15 lakh agents, covering more than 17,700 PIN codes. Its monthly transaction volume crossed 2.80 crore transactions. The company’s consolidated net profit rose to ₹20.09 crore in FY 2024-25 from ₹9.87 crore in the previous year.
RNFI completed its initial public offering in July 2024 and listed on the NSE Emerge (small and medium enterprise) platform of the National Stock Exchange. It disclosed the PA-P authorisation to the stock exchanges under Regulation 30 of the SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015, which requires listed companies to report material events.
A Growing Stack of Regulated Licences
The PA-P authorisation is the latest addition to a series of regulated permissions that RNFI holds across its group. The company describes this as building multiple regulated financial services on one common distribution, technology, and field infrastructure.
| Licence or Registration | What It Enables | Regulator |
|---|---|---|
| AD Category-II licence | Global money movement and foreign exchange services through RNFI Money Private Limited | RBI |
| AMFI ARN | Mutual fund distribution | AMFI |
| Insurance broking registration | Life and non-life insurance through Reliassure Insurance Brokers | IRDAI |
| Prepaid Payment Instrument (PPI) | Stored value wallets through Smart Payments Solutions | RBI |
| PA-P (in-principle) | Aggregation of physical, offline and in-store payments | RBI |
The company’s subsidiary RNFI Money Private Limited received the Authorised Dealer Category-II (AD-II) licence from the RBI in October 2025, which allows it to offer remittance and forex services more formally. The group also distributes mutual funds, sells insurance, and has interests in a business banking switch through its Paysprint subsidiary.
This multi-licence approach matters because it lets RNFI cross-sell many financial products through the same agent network. A shopkeeper who already uses Relipay for money transfers can potentially use the same platform for offline merchant payments once the PA-P licence becomes final.
In-Principle Approval vs Final Authorisation
An in-principle authorisation is a conditional green light from the RBI. It signals that the central bank is satisfied with the applicant on broad grounds, but the entity cannot begin full operations until it meets certain conditions and receives a final Certificate of Authorisation (CoA).
The RBI issues the final certificate only after the applicant fulfils the stipulated requirements within a given timeline. These conditions typically relate to capital adequacy, governance, technology standards, and compliance systems. In-principle approval is therefore a crucial stage, but it is not the same as a full licence.
RNFI’s own disclosure makes this clear. The company stated that the authorisation is subject to conditions specified by the RBI, and that final authorisation will follow once it meets the applicable requirements within the stipulated timeline. The listed entity, RNFI Services Ltd, is the one that received the authorisation, not a separate unlisted arm.
Why the PA-P Licence Matters for Offline Digital Payments
India’s digital payment growth has been led by online transactions, but a large share of retail spending still happens face to face at shops, kiosks, and small businesses. Bringing these offline transactions under a regulated aggregator framework extends the same protections that online customers already enjoy.
A PA-P licence lets an entity legally pool and settle in-store payments. This brings merchant onboarding, escrow, settlement discipline, and dispute handling under RBI supervision. For customers, it means clearer accountability if a payment fails or a refund is delayed.
The licence also has a strong financial inclusion angle. Small merchants in villages and small towns often lack the scale to negotiate directly with banks. An aggregator with a ready rural network can onboard them quickly. RNFI’s 2.15 lakh-strong Sahayak network, spread across more than 17,700 PIN codes, gives it a natural reach into exactly these under-served markets.
RBI norms require PA-P entities to complete merchant due diligence as per the KYC Directions. Small merchants, defined as physical merchants with turnover below ₹5 lakh a year and not registered under GST, get a lighter verification process. Medium merchants, with turnover below ₹40 lakh and no GST registration, face additional checks. New merchants have had to be onboarded under the full due diligence rules from 1 January 2026. Existing merchants had to be verified by 15 September 2026.
The Way Forward
For RNFI, the next step is to convert the in-principle approval into a final Certificate of Authorisation. The company must satisfy the RBI’s conditions, which centre on capital, governance, technology, and compliance standards. Only then can it begin aggregating offline payments at full scale.
For the wider payments industry, the PA-P framework closes a long-standing gap. Offline payment aggregation, which handles a very large volume of everyday retail transactions, now sits under the same rulebook as online aggregation. This is expected to improve transparency, strengthen merchant protection, and bring more small businesses into the formal digital payments system.
The bigger signal is regulatory. The RBI is steadily bringing every entity that touches customer money under a single, category-specific authorisation regime. For a company like RNFI, whose strength is its deep last-mile physical network, the PA-P licence turns that network into a regulated payments asset. How quickly it monetises this asset, and how smoothly it clears the final approval, will decide the payoff.
Key Takeaways
- RNFI Services Ltd received in-principle authorisation from the RBI to operate as a Payment Aggregator-Physical (PA-P) under the Payment and Settlement Systems Act, 2007.
- A PA-P handles transactions where the payment instrument and acceptance device are physically present together, covering face-to-face and in-store payments.
- The RBI (Regulation of Payment Aggregators) Directions, 2025, issued on 15 September 2025, created three categories: PA-O (Online), PA-P (Physical), and PA-CB (Cross Border).
- Under the PSS Act, 2007, the RBI is the designated authority; Section 4 bars operating a payment system without authorisation, and Section 7 lays down the criteria for granting it.
- Non-bank payment aggregators must maintain a minimum net worth of ₹15 crore at application and ₹25 crore by the end of the third financial year.
- RNFI Services, which operates the Relipay brand, was incorporated in 2015, is headquartered in New Delhi, and listed on NSE Emerge in July 2024.
- RNFI’s network covered about 2.15 lakh active Sahayaks across more than 17,700 PIN codes in FY 2024-25.
- An in-principle authorisation is conditional; a final Certificate of Authorisation (CoA) is granted only after the entity meets the RBI’s stipulated requirements.