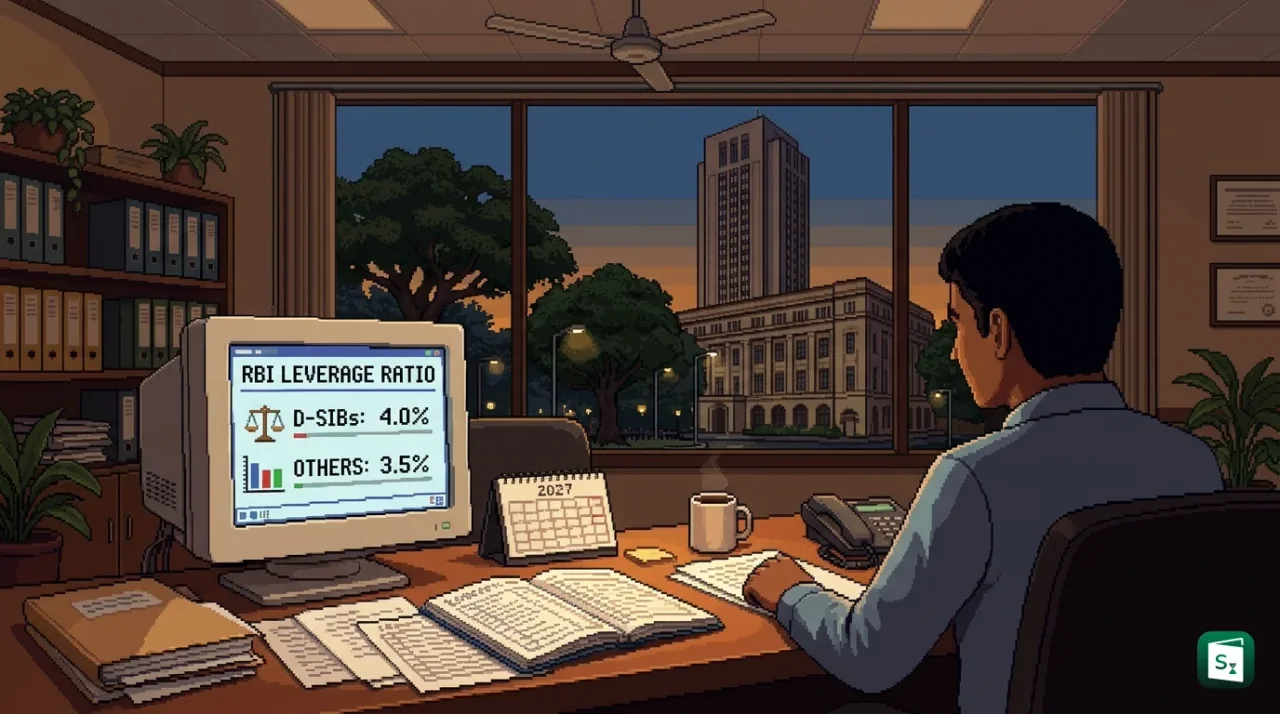
The Reserve Bank of India issued final directions on 23 October 2026 to revise the leverage ratio framework for commercial banks. The amended norms will come into force from 1 April 2027 and align Indian rules with the 2017 leverage ratio standard of the Basel Committee on Banking Supervision. The move tightens how banks measure total exposure while keeping the minimum ratios unchanged.
What Is Leverage Ratio in Banking?
The leverage ratio in banking is a simple check of how much of a bank’s own core capital supports its total business size. The RBI defines the Basel III leverage ratio as the capital measure divided by the exposure measure, expressed as a percentage. The capital measure is Tier 1 capital and the exposure measure is the sum of on-balance sheet and off-balance sheet exposures.
In plain words, the leverage ratio formula for banks is Tier 1 capital divided by total exposure multiplied by 100. Tier 1 capital is the highest quality capital that can absorb losses while the bank keeps running. It mainly includes common equity such as paid-up shares and disclosed reserves, plus Additional Tier 1 instruments. A higher ratio means the bank funds a larger share of its assets with its own capital and depends less on borrowed money.
This ratio is different from the common corporate idea of financial leverage. In company finance, leverage often means debt compared with equity or earnings. In banking regulation, the leverage ratio has a fixed meaning. It compares Tier 1 capital with total exposure without adjusting for risk. That makes it easy to calculate and hard to manipulate through complex risk models.
What Has the RBI Revised in the New Framework?
The RBI issued the Reserve Bank of India (Commercial Banks Prudential Norms on Capital Adequacy) Eleventh Amendment Directions, 2026 on 23 October 2026. The directions amend Chapter VII on leverage ratio in the Commercial Banks Prudential Norms on Capital Adequacy Directions, 2025. The RBI issued them under Section 35A of the Banking Regulation Act, 1949, which gives it power to issue directions to banks in public interest.
The revision follows a draft released on 7 August 2026 for public comments till 28 August 2026. The RBI reviewed stakeholder feedback and then issued the final rules. The central bank kept the implementation date unchanged. The amended directions will come into effect from 1 April 2027.
The core aim is alignment with the leverage ratio 2017 standard issued by the Basel Committee on Banking Supervision. The Basel Committee is the global standard setter for bank regulation and is housed at the Bank for International Settlements in Basel, Switzerland. India is a member of the Basel process. The RBI has now updated definitions, scope of consolidation, treatment of exposures, disclosure templates and reporting rules to match that global standard.
How Is the Leverage Exposure Measure Calculated?
The RBI has clarified that a bank’s total leverage exposure is the sum of four parts. These are on-balance sheet exposures, derivative exposures, Securities Financing Transaction (SFT) exposures, and off-balance sheet items. SFTs include transactions like repos, reverse repos, and securities lending and borrowing where cash or securities are exchanged with an agreement to reverse the deal later.
For on-balance sheet assets, banks must generally use gross accounting values. They cannot reduce the exposure by netting loans against deposits. They also cannot use physical or financial collateral, guarantees, or other credit risk mitigation to bring down the exposure, unless the directions clearly permit it. The rules also give specific treatment for cash pooling, unsettled trades, failed trades, long settlement transactions, and cases where the bank acts as an agent in SFTs.
For derivatives, the calculation method depends on size and reach. Banks with an international presence or with outstanding derivatives of ₹25,000 crore or more on a consolidated group basis must use the Standardised Approach for Counterparty Credit Risk (SA-CCR). Other banks may use either SA-CCR or the simpler Current Exposure Method (CEM). Collateral received generally cannot reduce replacement cost. The multiplier for potential future exposure stays fixed at one because the leverage ratio is a non-risk measure.
The RBI can temporarily exclude balances that banks hold with the RBI from the exposure measure in exceptional economic conditions. This helps smooth implementation of monetary policy. If such relief is given, the RBI will raise the minimum ratio in matching proportion so that resilience does not fall. Banks must then disclose the ratio both with and without the exemption. Both capital and exposure will be calculated on a quarter-end basis, though the RBI may allow daily or monthly averaging on request. Banks must meet the minimum ratio at all times.
How Credit Conversion Factor Works for Off-Balance Sheet Items
Off-balance sheet items are promises that can turn into real lending later. They include commitments, liquidity facilities, direct credit substitutes, acceptances, standby letters of credit, and trade letters of credit. The RBI converts them into credit equivalent amounts using a credit conversion factor (CCF).
A CCF turns the undrawn amount into an on-balance sheet equivalent. A 100% credit conversion factor will apply to certain specified items such as direct credit substitutes, guarantees of indebtedness, acceptances, forward asset purchases, and other credit substitutes not covered elsewhere. Lower factors apply to less risky items. For example, the global Basel design uses 50% for performance-related items like bid bonds and warranties, 40% for general commitments, 20% for short-term self-liquidating trade letters of credit linked to movement of goods, and 10% for commitments that the bank can cancel at any time without notice.
What Are the Rules for D-SIBs and G-SIB Branches?
The RBI has kept a differentiated minimum to reflect systemic risk. A bank whose failure can disrupt the whole financial system must hold more capital.
| Bank Category | Minimum Leverage Ratio | How It Applies |
|---|---|---|
| Domestic Systemically Important Banks (D-SIBs) | 4% | Tier 1 capital must be at least 4% of total exposure at all times |
| Other banks | 3.5% | Tier 1 capital must be at least 3.5% of total exposure at all times |
| Indian branches of Global Systemically Important Banks (G-SIB branches) | 3.5% plus leverage ratio buffer | Base 3.5% plus the G-SIB buffer applicable to the parent group, including any extra buffer set by the home regulator |
D-SIBs are banks that are too big to fail in the domestic context. The RBI declares them under its D-SIB framework of 2014, updated in 2023, based on size, interconnectedness, substitutability, and complexity. State Bank of India, HDFC Bank, and ICICI Bank were named as D-SIBs in the 2025 list (as of December 2025). G-SIBs are large global banking groups identified by the Basel Committee and the Financial Stability Board. Their Indian branches must hold the extra buffer in India in proportion to their India operations.
If a G-SIB branch fails to meet its buffer, the RBI will impose capital distribution constraints. This can limit repatriation of profits to the head office and other payouts. The cut depends on both the Common Equity Tier 1 (CET1) risk-based ratio and the Tier 1 leverage ratio. CET1 is the purest form of capital, mainly equity shares and retained earnings. If the branch misses one requirement, the related conservation standard applies. If it misses both, the higher of the two standards applies.
The RBI rejected requests to soften these rules. It did not accept the suggestion to cap the G-SIB branch requirement at the home country level or to lower it to the Basel minimum of 3%. It also rejected requests to set the buffer based only on the Indian branch’s size and to extend the April 2027 deadline.
Why Leverage Ratio Is Important Alongside Capital Adequacy Ratio
The leverage ratio works as a backstop to the risk-based Capital Adequacy Ratio (CAR). CAR compares capital with risk-weighted assets. Risky loans get higher weights and safe assets like government bonds get lower weights. This is useful but depends on models and ratings that can sometimes misjudge risk.
The leverage ratio does not adjust for risk. It counts all exposures in full. That stops banks from building very large balance sheets with thin capital even when risk weights look low. It also captures off-balance sheet promises and derivative exposures that can create sudden stress. The global financial crisis showed how such hidden leverage can force rapid asset sales and cut lending to the economy.
| Feature | Leverage Ratio | Capital Adequacy Ratio (CAR) |
|---|---|---|
| What it compares | Tier 1 capital against total exposure | Total capital against risk-weighted assets |
| Adjusts for risk | No, all exposures count at face or converted value | Yes, assets get different risk weights |
| Minimum in India for large banks | 4% for D-SIBs under new rules | 11.5% including buffers for most banks, with higher CET1 for D-SIBs |
| Main purpose | Simple backstop against excessive borrowing | Risk-sensitive cushion against expected and unexpected losses |
On transparency, banks must publicly disclose their quarterly Basel III leverage ratio on both standalone and consolidated bases. They must also report the ratio to the RBI’s Department of Supervision with full details of capital and exposure. In addition, they must publish Template LR1 and Template LR2 under Pillar 3 disclosure norms. LR1 reconciles published accounting assets with the leverage exposure measure. LR2 breaks up the exposure into its main components. This helps markets see window dressing around reporting dates, especially in SFTs.
When Do the Revised Norms Take Effect and What Lies Ahead
The revised framework will apply from 1 April 2027. The RBI has said banks must meet the minimum at all times, not just on reporting days. Quarter-end figures will form the basis for public disclosure. Banks that want to use daily or monthly averaging must seek prior RBI approval and then use the method consistently.
Supervision will also tighten. If reported exposures do not reflect true leverage, the RBI can ask for more data, direct improvements in leverage management, or impose extra capital under Pillar 2. Pillar 2 is the part of the Basel system where the supervisor can demand extra capital for risks not fully covered under standard rules. The RBI has also agreed to update its Centralised Information Management System (CIMS) reporting format if needed so that filings match the new definitions.
For banks, the immediate task is to upgrade systems for SA-CCR calculation, SFT tracking, and CCF mapping. For the financial system, the gain is a cleaner and more comparable measure of leverage across banks. Over time, this should reduce the chance of sudden deleveraging that can hurt credit flow to firms and households.
Key Takeaways
- The RBI Eleventh Amendment Directions, 2026 revising the leverage ratio framework were issued on 23 October 2026 and take effect from 1 April 2027.
- The Basel III leverage ratio is Tier 1 capital divided by total exposure, expressed as a percentage.
- Minimum leverage ratio is 4% for D-SIBs and 3.5% for other banks, while G-SIB branches must hold 3.5% plus the applicable buffer.
- Total exposure covers on-balance sheet assets, derivatives, SFTs, and off-balance sheet items, with a 100% credit conversion factor for specified items.
- Banks must disclose the ratio quarterly on standalone and consolidated bases using Pillar 3 Templates LR1 and LR2 and report to the RBI’s Department of Supervision.