
The Securities and Exchange Board of India issued three circulars on 5 November 2026 covering mutual fund settlement, accredited investors and currency derivatives. Mutual fund schemes can net cash market fund obligations from 1 April 2027. Accredited investor and rupee derivative norms take effect immediately with tighter exposure limits.
What Is SEBI and How Does It Regulate the Market?
The Securities and Exchange Board of India (SEBI) is the apex regulator of the Indian securities market. It protects investor interests, promotes market development and regulates stock exchanges, brokers, mutual funds, Foreign Portfolio Investors and other intermediaries. SEBI functions under the overall oversight of the Ministry of Finance.
SEBI was constituted as a non statutory body on 12 April 1988 through a government resolution. It became a statutory body when the SEBI Act, 1992 came into force on 30 January 1992. The Act was passed after the early 1990s expansion of equity markets exposed the need for a legally empowered regulator. SEBI is headquartered in Mumbai, with regional offices in New Delhi, Chennai, Kolkata and Ahmedabad.
SEBI is a quasi legislative and quasi judicial body. It frames regulations for listings, mutual funds, takeovers and insider trading, conducts inspections and inquiries, and can issue directions and impose penalties. Its core mandate covers issuers who raise funds, investors who need accurate disclosure and protection, and intermediaries who need fair and competitive standards.
How Will Mutual Fund Net Settlement Work From April 2027?
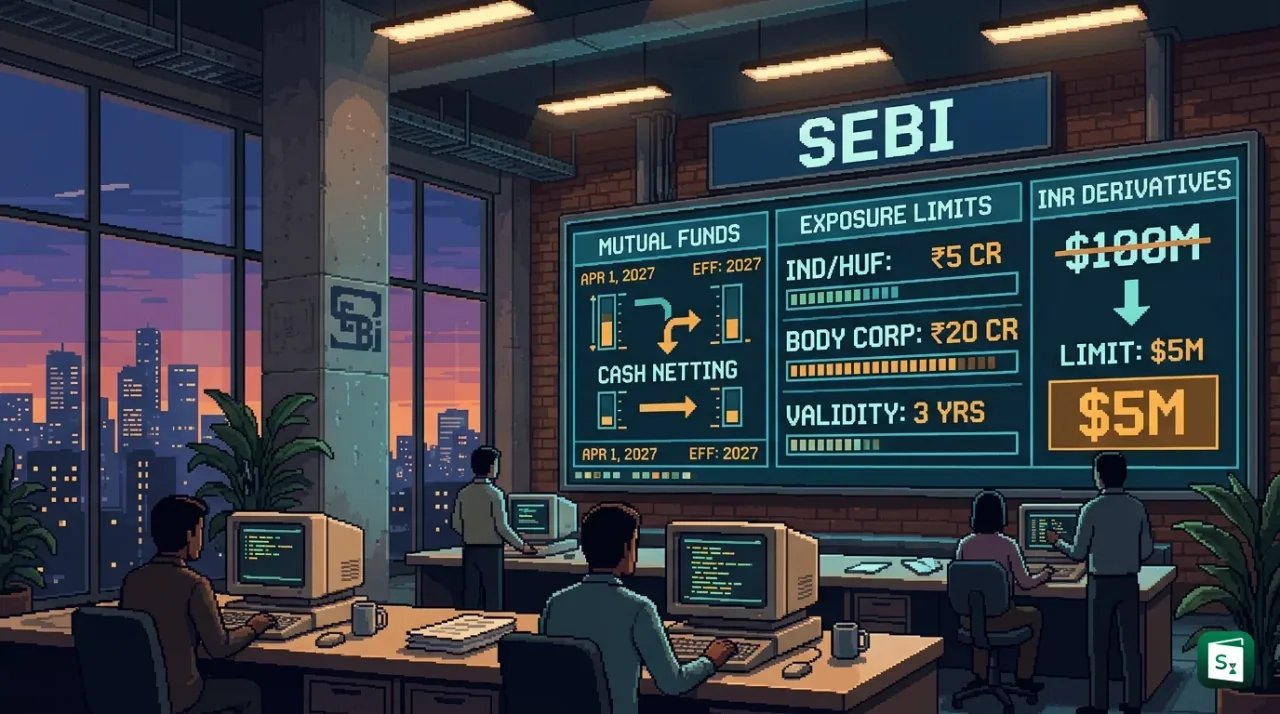
The mutual fund net settlement framework allows a mutual fund scheme to offset cash payable against cash receivable for selected trades in the equity cash segment. The facility starts on 1 April 2027 under SEBI circular HO/24/13/(1)2026-IMD-POD-2/I/25242/2026 dated 5 November 2026. It covers only the money leg. The securities leg continues to settle on a gross and delivery backed basis.
At present no institutional investor is allowed to do intra day square off. All cash market trades are delivery backed and custodians settle fund obligations on a gross basis. This raises temporary funding needs on busy days such as index rebalancing. SEBI had given the same relief to Foreign Portfolio Investors (FPIs) on 24 April 2026 for implementation by 31 December 2026. The new circular extends equivalent treatment to mutual fund schemes.
Netting is permitted only within the same mutual fund scheme and within the same settlement cycle. SEBI has barred three things clearly. No netting is allowed across different schemes of the same fund, no adjustment is allowed between schemes or portfolios, and no inter scheme funding can arise from the process. The asset management company and the custodian must ensure that scheme accounting, daily net asset value computation, asset allocation and investment limits remain unaffected.
What Is an Outright Transaction and What Is Excluded?
An outright transaction means either a purchase or a sale in a security in the same settlement cycle, but not both, undertaken by a mutual fund scheme. If a scheme only buys shares of company A in that cycle, it is an outright purchase. If it only sells shares of company C, it is an outright sale. Only outright purchases and outright sales can be netted to arrive at the net fund obligation.
If a scheme both buys and sells the same security in the same settlement cycle, the trades are non outright transactions for that cycle. They stay outside netting and settle on a gross basis. This rule preserves the ban on intra day square off by institutions. The framework also excludes derivative transactions, securities lending and borrowing, short sale related transactions and any other transaction not expressly covered.
The treatment of balance amounts follows two clear rules. If outright sales are lower than outright purchases, the scheme must fund the residual amount. If outright sales are higher than outright purchases, the excess cannot be used to meet purchase obligations of non outright trades. Those non outright purchases must be funded separately.
| Security | Buy value | Sell value | Treatment |
|---|---|---|---|
| A | ₹1,000 | Nil | Outright purchase, eligible for netting |
| B | ₹1,000 | ₹2,000 | Non outright, stays on gross basis |
| C | Nil | ₹2,000 | Outright sale, eligible for netting |
Under gross settlement the scheme in this illustration pays in ₹2,000 and receives ₹4,000. Under net settlement, A and C are netted, so pay in falls to ₹1,000 and pay out falls to ₹3,000. Obligations for B remain gross. Securities Transaction Tax (STT) and stamp duty continue on a delivery basis, and securities move gross between the scheme and the custodian.
The Association of Mutual Funds in India (AMFI) will frame implementation standards in consultation with clearing corporations, stock exchanges, custodians and other stakeholders. The standards will cover file formats, confirmation timelines, reconciliation, audit trails and handling of rejected or modified trades. Trustees must review implementation in the interest of unit holders, and asset management companies and custodians must jointly confirm system readiness before the launch.
What Is the New Accredited Investor Framework?
An accredited investor is a person or entity that meets SEBI specified income, net worth or market exposure tests and is recognised as capable of understanding complex product risk. Accreditation acts as a gateway to lighter ticket size rules for Alternative Investment Funds (AIFs), Portfolio Management Services (PMS), Specialized Investment Funds (SIFs), Angel Funds and co investment vehicles. It changes eligibility limits, not the underlying market risk of the product.
SEBI revised the framework through amendments to the SEBI (Alternative Investment Funds) Regulations, 2012 notified on 15 October 2026 and circular HO/19/34/11(6)2026-AFD-POD1/I/25244/2026 dated 5 November 2026. The circular took effect immediately. The key change is an optional manager led accreditation route in addition to certificates from recognised accreditation agencies, which are subsidiaries of stock exchanges or depositories.
A manager means the manager of an AIF, the asset management company of an SIF, or a portfolio manager. The manager can determine and record accredited status at onboarding or during a scheme, after verifying documents. A determination is valid for 3 years from the date of accreditation and is recognised across managers of the same group for AIFs, SIFs and portfolio management services. It must be recorded in writing with the date and validity period. An investor who holds a valid agency certificate need not undergo fresh determination during its validity. A person who is accredited at onboarding remains treated as accredited for the remaining life of that scheme.
What Counts as Securities Market Exposure?
SEBI has added securities market exposure as an additional criterion alongside income and net worth. The minimum exposure is ₹5 crore for individuals, Hindu Undivided Families (HUFs), family trusts and sole proprietorships, and ₹20 crore for body corporates and trusts other than family trusts. The thresholds were chosen after analysis of holdings data as on 30 April 2026, which showed that higher holdings correlate with greater risk taking capacity. SEBI estimated that about 3.7 lakh investors could meet the test, compared with about 96,000 existing AIF investors.
The following holdings qualify as securities market exposure:
- Securities held in dematerialised form, including listed equity and debt
- Mutual fund investments held through folios
- Unlisted securities held in dematerialised form
- Investments in overseas securities markets
- Investments under the National Pension System (NPS)
For demat holdings, the value in the eCAS consolidated statement as on the statement date is used. For unlisted and overseas holdings not valued in eCAS, the applicant must furnish a certificate from a practising chartered accountant stating the nature of securities, valuation date and value. Bank deposits, real estate and gold are not counted.
| Eligibility test | Document for verification |
|---|---|
| Income | Latest Income Tax Return, or certificate from a practising chartered accountant |
| Net worth | Latest audited financial statements, or net worth certificate not older than six months |
| Securities market exposure | eCAS summary from a depository not older than six months, or chartered accountant certificate showing the threshold was met in the last six months |
Accredited status gives concrete relaxations. The ₹1 crore minimum for AIFs, ₹50 lakh minimum for PMS and ₹10 lakh minimum for SIFs do not apply to accredited investors. The minimum for Special Situation Funds falls from ₹10 crore to ₹5 crore. A Large Value Fund for Accredited Investors, where each investor commits at least ₹25 crore, can launch after filing its placement memorandum, extend tenure up to five years with two thirds consent, and hold higher concentration limits.
Why Did SEBI Cut INR Currency Derivative Limits to $5 Million?
A currency derivative is a contract traded on a recognised stock exchange to buy or sell foreign currency at a future date and price. Contracts involving the Indian Rupee (INR), such as dollar rupee pairs, are used by importers, exporters and investors to hedge exchange rate risk. The same contracts can also be used for speculative bets when no genuine business exposure exists.
SEBI has reduced the no questions asked window sharply. Domestic clients and Foreign Portfolio Investors (FPIs) can now take long or short positions in INR linked currency derivatives without proving underlying exposure only up to a single limit of $5 million in notional value outstanding at any point. The limit applies across all currency pairs involving INR put together and across all recognised stock exchanges combined. The earlier limit was $100 million.
The change aligns SEBI rules with the Reserve Bank of India (RBI) circular A.P. (DIR Series) Circular No. 25 dated 10 October 2026 on risk management and inter bank dealings. The RBI cut the threshold for foreign exchange derivatives involving INR without underlying exposure from $100 million to $5 million across all authorised dealers. SEBI amended clause 5.3.3 of its Master Circular for Stock Exchanges and Clearing Corporations dated 30 December 2024 to match that stance.
Two additional conditions apply beyond the headline cap. FPIs must ensure that short positions across all foreign currency rupee contracts do not exceed $5 million. To take long positions above $5 million, FPIs must hold underlying exposure in Indian debt or equity securities, including units of equity and debt mutual funds. Domestic clients can exceed $5 million only under the conditions in the RBI Master Direction on Risk Management and Inter Bank Dealings dated 5 July 2016 as amended, and the October 2026 circular.
The RBI package also tightened related discipline to support orderly functioning of the foreign exchange market. Authorised dealers cannot allow rebooking of a cancelled rupee linked derivative contract, though rollover on maturity remains permitted. Users must give an undertaking that the same exposure has not been hedged with another dealer. For rupee linked contracts to hedge current account exposure where foreign currency is purchased against the rupee, dealers must keep a cash reserve with the RBI equal to 20 percent of the rupee value of the notional amount for transactions above $2 million.
Stock exchanges and clearing corporations must update systems, amend bye laws, inform brokers and clearing members, publish the provisions and report implementation status to SEBI. For genuine hedgers with documented trade or investment exposure, hedging remains available. For traders without exposure, the scope for large unhedged rupee bets has narrowed substantially.
Key Takeaways
- Mutual fund schemes can net fund obligations for outright cash market trades from 1 April 2027 under the SEBI circular dated 5 November 2026.
- Netting is allowed only within the same scheme and settlement cycle, while securities settle gross and STT and stamp duty stay on a delivery basis.
- New accreditation route allows manager led approval valid for 3 years, with ₹5 crore exposure for individuals, HUFs, family trusts and sole proprietorships and ₹20 crore for body corporates and other trusts.
- Domestic investors and FPIs can hold $5 million in INR currency derivatives without underlying exposure, down from $100 million, across all INR pairs and exchanges combined.
- SEBI, set up on 12 April 1988 and made statutory on 30 January 1992 under the SEBI Act, 1992, is headquartered in Mumbai and works under the Ministry of Finance.